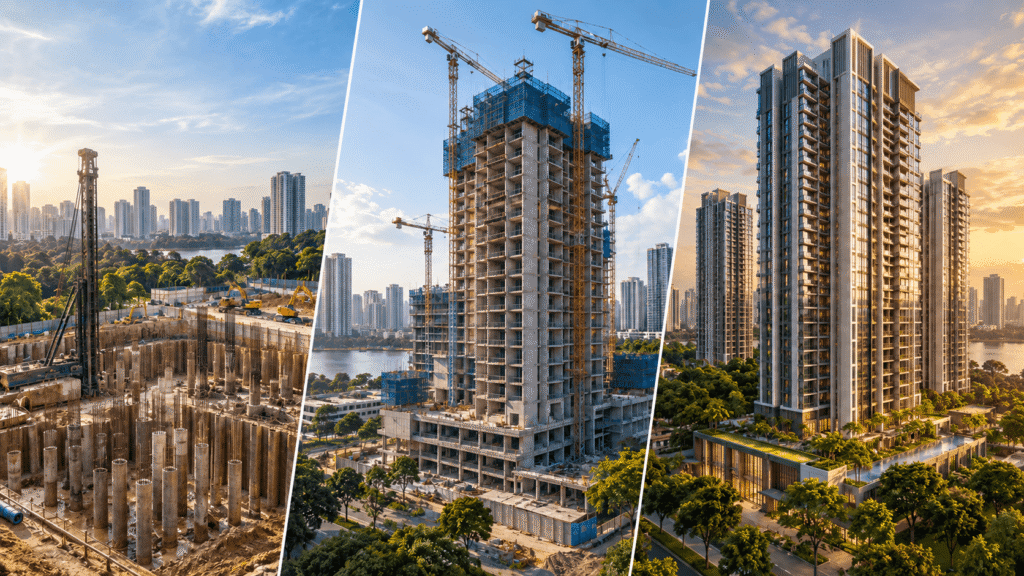
Committing to a Building Under Construction loan in Singapore means financing a property that doesn’t exist yet, which comes with a different set of expectations than buying something you can walk through today. Beyond the progressive payment mechanics, buyers need to understand how the loan behaves over the full construction period, not just how it’s disbursed.
This guide focuses on what a Building Under Construction loan in Singapore actually involves once you’ve committed: how your BUC home loan Singapore obligations evolve, what happens if your finances or the project timeline change mid-construction, and what to watch for with a new launch condo financing Singapore purchase before you sign.
Your Purchase Price Is Locked, and Your Loan Is Committed From Approval
One of the most important things to understand about a Building Under Construction loan in Singapore is that your purchase price is fixed at the point you exercise the Sale and Purchase Agreement, regardless of how long construction takes or how the property market moves in the meantime. Your loan itself, once approved via the Letter of Offer, is committed; each subsequent disbursement is released automatically as the developer certifies each construction milestone, not through a fresh credit review at every stage.
What can genuinely affect your position over the construction period is your own financial planning around the loan, rather than the bank reopening your file. If your income or existing debt changes significantly during construction, it matters most if you later apply for a new loan for another property, for instance, rather than for the BUC loan already in progress.
What Changes If Your Financial Situation Shifts Mid-Construction
Because construction can take two to four years from purchase to Temporary Occupation Permit, it’s worth expecting that your circumstances may look different by the time the final tranches of your under-construction property loan in Singapore are disbursed. A few scenarios worth planning for:
● Taking on new debt — a car loan, another property, or a business loan during the construction period will factor into your TDSR calculation for any new loan application made later, even though it doesn’t reopen your existing BUC loan.
● A change in employment or income matters most if you’re relying on future refinancing at TOP, since the bank will reassess your profile fresh at that point.
● Selling your existing home while your Building Under Construction loan in Singapore is still disbursing has ABSD implications if the sale doesn’t happen within the required timeline for ABSD remission.
Buyers upgrading from an existing property should plan the sale timeline of their current home carefully alongside their BUC purchase, since the two financial events are often more tightly linked than buyers initially expect.
BUC Mortgage Disbursement: What Can Cause It to Slow Down
BUC mortgage disbursement isn’t always a smooth, predictable drip in line with the payment schedule. A few factors can affect timing:
Construction delays – If a project falls behind schedule, the milestone that triggers your next disbursement simply doesn’t happen until the developer reaches it, which pushes back your loan drawdown accordingly.
Bank documentation requirements – Each progress payment claim typically requires the developer to submit certification, and the bank may take time to process and verify this before releasing funds.
Valuation reviews – In rarer cases, banks may reassess valuation partway through construction, particularly if market conditions have shifted significantly since the original purchase.
None of these factors are within the buyer’s direct control, which is why BUC mortgage disbursement should be approached with the expectation of some timeline flexibility rather than treating the original schedule as fixed to the week.
Interest Rate Expectations Over the Construction Period
A Building Under Construction loan in Singapore is floating-rate only for the full construction period, typically pegged to SORA plus a bank spread; fixed-rate packages generally aren’t available until the property reaches TOP. This means your interest cost during construction moves with the broader rate environment, though the impact is softened somewhat since interest only accrues on the portion of the loan actually disbursed at each stage, which is lower than the full loan amount in the early years.
Buyers should also expect that BUC packages, more so than resale property loans, vary between banks in terms of lock-in flexibility during construction. Some banks allow refinancing without penalty before TOP; others don’t. Confirming this at the outset avoids an unwelcome surprise if you want to reassess your rate before your unit is completed. Our home loan comparison service reviews these package-specific differences across multiple banks before you commit.
New Launch Condo Financing Singapore: Budgeting Beyond the Loan
Buyers focused solely on the loan itself sometimes underbudget for costs that sit alongside a new launch condo financing Singapore purchase. Beyond the purchase price and progressive payments, plan for:
1. Stamp duties – Buyer’s Stamp Duty and any applicable Additional Buyer’s Stamp Duty, both due early in the process, well before your BUC mortgage disbursement schedule reaches its later stages
2. Legal fees – For reviewing the Sale and Purchase Agreement and handling the eventual mortgage
3. Interim accommodation – If you’re selling your current home before your new unit completes, factor in the gap period
4. Renovation and furnishing – Due only at TOP, but worth budgeting for well in advance given the loan disbursement timeline is known upfront.
Underestimating these adjacent costs is one of the more common gaps buyers encounter when financing a new launch condo financing Singapore purchase, since the headline loan and payment schedule can create a false sense that the loan covers the full journey to move-in.
What Happens If the Project Is Delayed Beyond Expectations
Construction delays affect your Building Under Construction loan in Singapore primarily by extending the timeline over a which disbursement occurs, rather than changing what you owe. Your total loan amount and purchase price remain as originally agreed. However, a longer construction period does mean a longer stretch of partial disbursement and correspondingly lower interim repayments, followed by a later shift to full repayment once TOP is issued and the final tranche is disbursed.
Buyers juggling an existing home loan alongside a delayed Building Under Construction loan in Singapore should factor in the possibility of a longer overlap period between the two obligations when assessing affordability at the outset, rather than assuming the original completion date is
guaranteed. Our bank vs HDB loan comparison is useful background if you’re weighing how a BUC purchase interacts with an existing HDB loan during this overlap period.
Frequently Asked Questions
Can my loan amount change during construction of a BUC unit?
Your purchase price and approved loan amount are fixed once your Letter of Offer is signed. Disbursement proceeds automatically as construction milestones are certified, not through repeated credit reviews.
What happens to my Building Under Construction loan in Singapore if the project is delayed?
The total loan amount and price stay the same, but disbursement is spread over a longer period, meaning a longer stretch of partial repayments before the loan shifts to full repayment at TOP.
Is a fixed interest rate available for a BUC loan?
Generally no. BUC loans are floating-rate only, pegged to SORA plus a bank spread, for the full construction period. Fixed-rate packages typically only become available once the property reaches TOP.
Should I budget for anything beyond the purchase price and loan repayments?
Yes, stamp duties, legal fees, potential interim accommodation if selling your current home, and renovation costs should all be planned for separately from the loan schedule itself.
How does selling my existing property affect a BUC purchase in progress?
If you’re relying on ABSD remission, the sale of your existing property generally needs to happen within a specific timeline, which should be planned alongside your BUC purchase rather than left until later.
Ready to plan the financing for your Building Under Construction purchase with a clear view of what’s ahead? Get a free, no-obligation consultation from FinanceGuru’s advisory team.
FinanceGuru
12 Arumugam Road, #02-02B
LTC Building, Suite B,
Singapore S409958
Contact:+65 9890 9090